Research — October 28, 2026
AMMs Without the Blockchain: Better Market Makers?
The SEC’s Innovation Exemption brings automated market makers (AMMs) into the discussion of trading tokenized stocks. Its broader significance, however, may lie in the liquidity pool itself: investor capital made available under established pricing rules, rather than through a liquidity provider’s decision to commit to a particular trade. Could an AMM operating on an exchange or alternative trading system (ATS) - without blockchain - offer a different approach to securities-market liquidity?
AMMs may be well suited to a decentralized finance (DeFi) marketplace. But blockchain may not be the best implementation for an AMM serving institutional securities trading.
Today, obtaining size can involve working an order, exposing interest, or seeking a provider willing to take the other side on terms that justify the risk. Often, small displayed quotes serve as probes, exposing buy-side intentions without offering meaningful size. Predatory strategies can exploit that information before the institution completes its order. An AMM offers a different sequence: the trader can assess available pool liquidity, expected execution price, and price impact before revealing an intention to trade.
How the Pool Works
An AMM executes against contributed assets under established pricing rules. Investors supply a pair - say, XXX and USD - and receive interests representing their participation. A buyer adds USD and receives XXX; a seller does the reverse. Trading fees compensate contributors and, depending on the arrangement, the platform.
In a basic constant-product AMM, a pool holding 1,000 XXX and 10,000 USD starts at 10 USD per XXX for a very small trade, before fees. Buying XXX removes it and adds USD, raising the price; selling does the reverse. A deeper pool reduces price impact.
Typically, the pool’s pricing formula and trading activity determine its price, while arbitrage helps keep it aligned with other markets. Other designs can incorporate an external reference price.
The trader enters a proposed trade, and the interface returns an indicative execution price and estimated price impact. The trader can then assess the expected economics and decide whether to proceed. Intervening trades may change the result, but the assessment begins with capital already available in the pool - not uncertainty about whether a liquidity provider will offer size and on what terms.
The Limits of Discretionary Liquidity
Principal liquidity providers perform a valuable function. They commit capital and manage positions that otherwise might require an institution to wait, divide an order, or accept a different price.
In an ATS, however, the limitation is not merely that a provider might withdraw. There may be no standing commitment to offer liquidity in the first place. Trading venues compete to attract providers, who assess each opportunity against their own risk limits and trading objectives.
The specialist model linked a valuable franchise with defined market-maintenance responsibilities. Today’s designated market makers retain obligations, albeit watered down over time. Most off-exchange liquidity providers have no equivalent affirmative obligation to step forward and provide liquidity.
Off-exchange liquidity providers assess whether a trade offers a credible and profitable route out of the resulting position. Their willingness to provide size is driven by that assessment, rather than an affirmative responsibility to make a market.
What if liquidity were instead provided under a defined, transparent pricing formula rather than at a liquidity provider’s discretion?
On-Chain AMMs Have Limitations Too
Front-running, price impact, and slow execution can make on-chain AMMs poorly suited to larger trades. Processing capacity and latency can constrain institutional activity, while publicly submitted transactions may be visible before execution without guaranteed submission-order priority.
Transaction ordering creates opportunities for maximal extractable value (MEV): value captured by selecting, excluding, or sequencing transactions within a block. MEV encompasses several strategies, including arbitrage and front-running. In a sandwich attack, an attacker buys ahead of a customer’s purchase, pushing the pool’s price against that customer, then sells immediately afterward to profit from the movement. Participants can pay for preferred inclusion and ordering, making execution priority itself a source of revenue.
A shallow pool produces substantial price impact. Contributors can also underperform simply holding the contributed assets - a risk known as impermanent loss. Liquidity bands allow contributors to specify the price ranges in which they participate but introduce their own risk and availability trade-offs. Those design choices are beyond the scope of this article.
A Securities-Market Implementation
An exchange or ATS could build a pool’s operating logic directly into its platform code. Execution would not depend on block construction or require broadcasting pending trades to a public blockchain queue. The platform could apply its own controlled sequencing and confidentiality arrangements.
Transparency would come from published pricing, fees, allocation, trade-handling, and parameter-change rules. Audit trails and applicable regulatory oversight would provide accountability. A smart contract is one implementation of rules, not a prerequisite for making them visible and enforceable.
The terms governing contributed liquidity matter equally. Contributors would agree to withdrawal conditions, inventory limits, and trading pauses. Within those terms, liquidity would be available under established rules rather than a provider’s discretionary assessment of each trade.
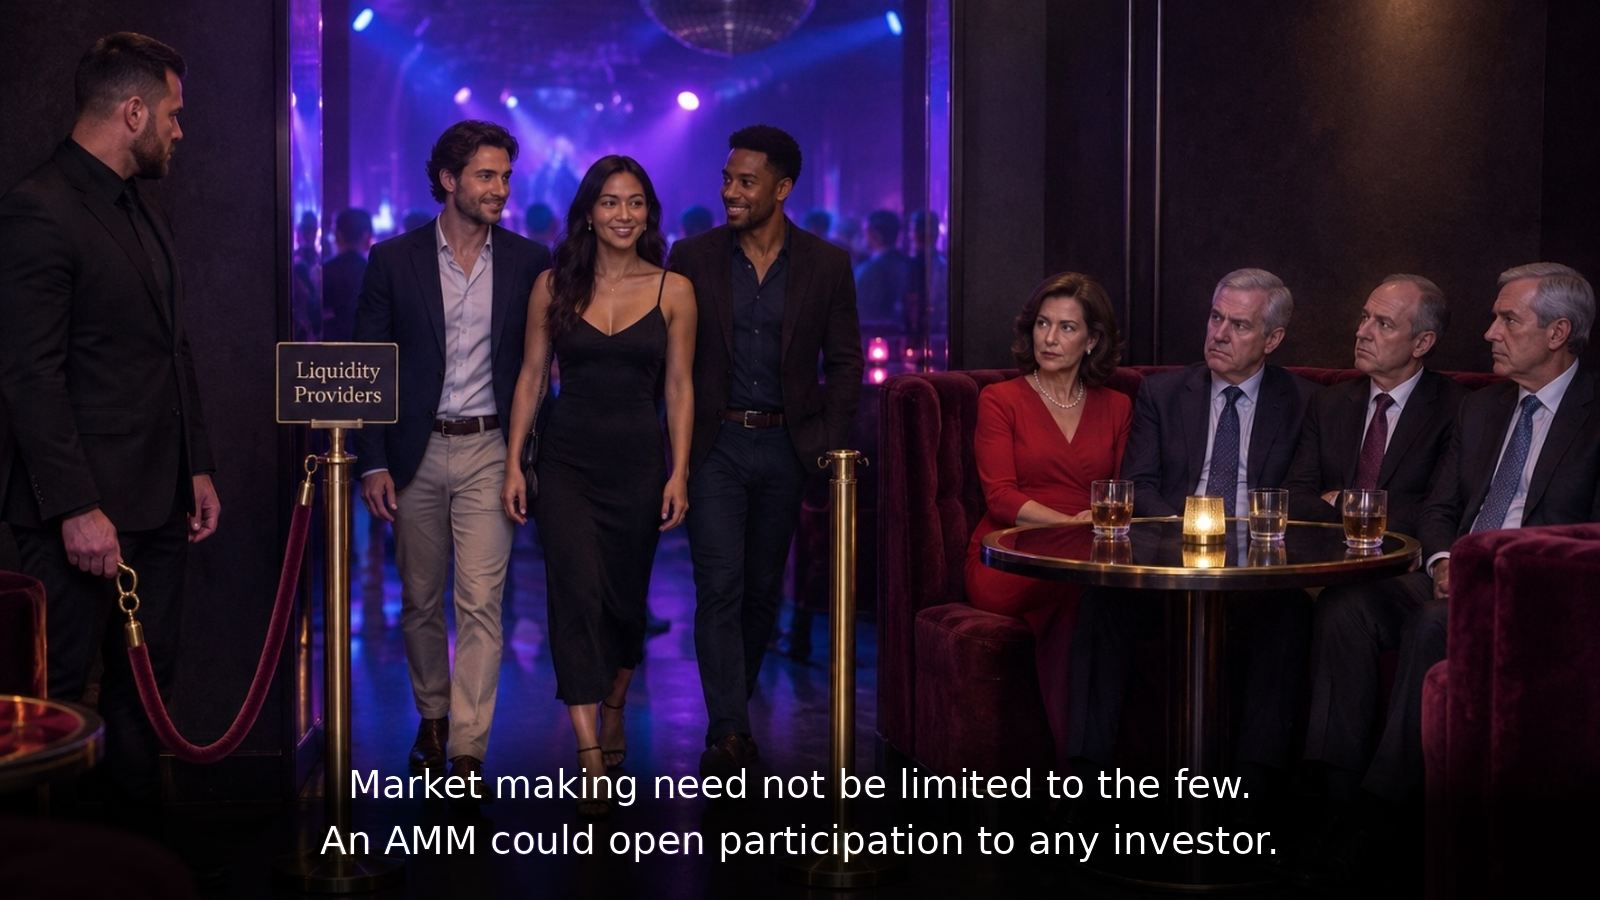
A broader group of eligible investors could contribute without building individual market-making businesses. Their investment horizons need not match those of firms seeking rapid inventory turnover. The trading fee could be explicit and set low, while inventory risk rests with contributors accepting the terms. Attracting sufficient liquidity would still require viable returns for contributors. But participation in market making would no longer require operating a market-making firm.
This would be another execution window alongside central limit order books and traditional trading channels - not a replacement. Traders could enter a proposed trade, assess its indicative price and price impact, and compare that outcome with other execution choices.
Where It Could Matter
Small- and mid-cap stocks could benefit from a different liquidity model. Longer inventory holding periods for liquidity providers make liquidity expensive, and investors factor the resulting entry and exit costs into their investment decisions. A pool offering lower fees and spreads, with both clearly defined, could make these securities more attractive relative to other investments.
For highly liquid stocks, a deep pool could offer another execution window for large institutional trades, allowing traders to assess expected execution costs before exposing an order. The opportunity extends from improving liquidity where it is scarce to making substantial liquidity more accessible where trading is already active.
Off-Chain AMMs Could Offer a New Approach to Liquidity
Crypto markets have produced innovations that deserve consideration beyond their original setting. The liquidity pool is one: a way for investors to participate in market making and for traders to access liquidity under transparent pricing rules. Neither function requires blockchain.
Implemented on an exchange or ATS, an AMM could broaden who supplies liquidity and offer traders another choice alongside existing markets. The innovation would be more than a new execution mechanism. It would be a different way to organize liquidity provision and participate in it.
The broader significance of the Innovation Exemption may therefore extend beyond the trading it permits. It invites consideration of a liquidity model whose most useful securities-market implementation may not be on-chain at all.
Comments